What a reroof costs in Pueblo
In a hail market the headline price is rarely what you pay. The deductible is, and on most Colorado policies it is a percentage rather than a flat sum.
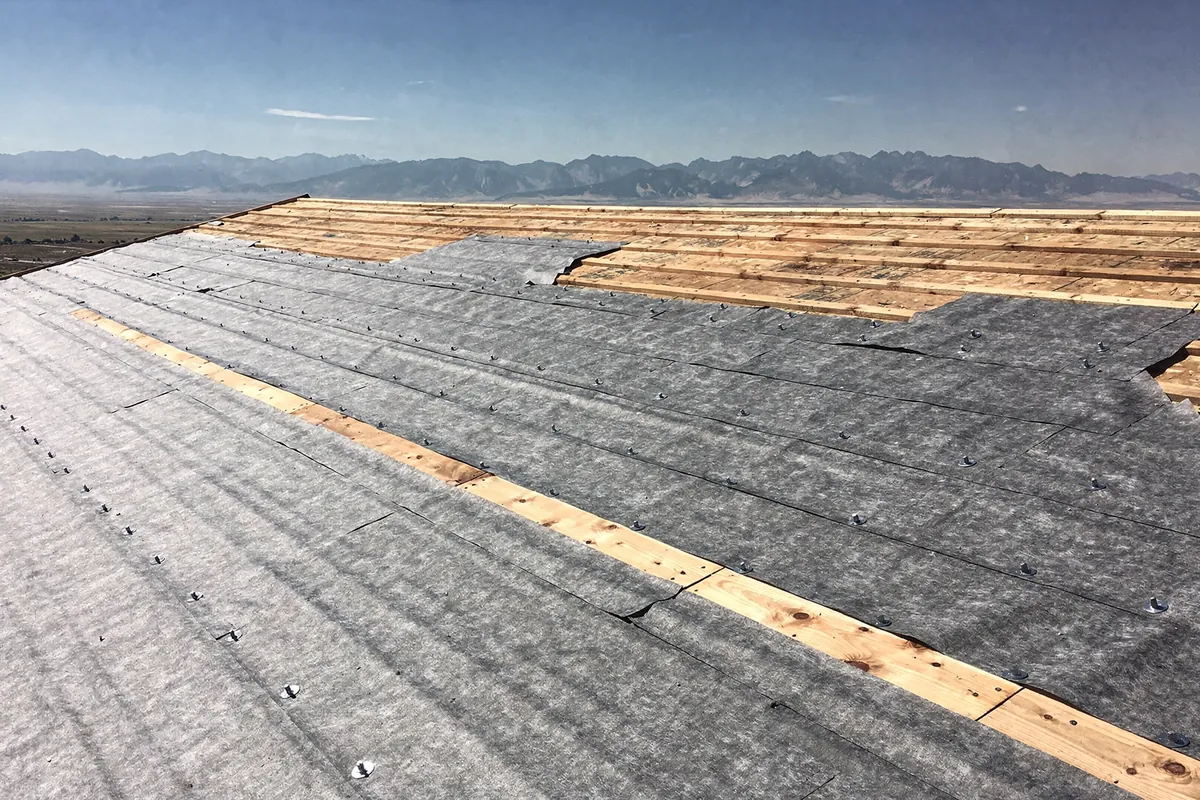
Two numbers matter in a hail market and only one of them appears in a bid.
The job cost is what the work is worth, and after a storm an insurer’s estimate usually sets the frame for it. The deductible is what leaves your account, and it is the one most people get wrong.
Start with the deductible
Most Colorado wind and hail policies use a percentage deductible rather than a flat amount. One or two percent of the dwelling coverage limit is common.
On a $350,000 dwelling limit, two percent is $7,000. People who assumed $1,000 and budgeted accordingly have a bad afternoon when the settlement arrives.
Read the declarations page before you do anything else. If the damage is marginal, the deductible sometimes makes a claim not worth filing, and that is a decision better made at the start.
If you are paying cash
Straightforward single storey home, full tear off, architectural asphalt. Bands local companies tend to quote. Not a quote.
| Roof size | Standard architectural | Class 4 impact resistant |
|---|---|---|
| 15 to 18 squares | $8,500 to $13,000 | $11,000 to $16,500 |
| 18 to 24 squares | $10,500 to $16,500 | $13,500 to $21,000 |
| 24 to 32 squares | $14,000 to $22,000 | $18,000 to $28,000 |
| Steep or two storey | add 15 to 30 percent | add 15 to 30 percent |
A square is 100 square feet of roof surface, always more than the floor area underneath.
What moves the number here
Altitude and ultraviolet. At Pueblo’s elevation the sun works harder on asphalt than the shingle’s rating assumes. It is an argument for a better shingle rather than the cheapest one, and for paying attention to the wind and impact ratings rather than the colour.
Temperature swing. Large daily swings expand and contract every component. Fasteners, flashing and sealant all live a harder life than in a stable climate, which puts the value on the details rather than the field.
Decking. Unknown until the tear off. A per sheet price in the contract, agreed in advance, is not optional.
Ventilation. Balanced intake and exhaust. An attic that cannot breathe cooks the deck in summer and invites condensation in winter, and in this climate winter is the one people forget.
Comparing bids when an insurer has written the scope
The insurer’s estimate is a useful anchor, because every contractor is pricing broadly the same list. Where bids differ, it is usually one of three things: what they intend to do about items the adjuster missed, what quality of material they are putting against the line, and whether they are replacing or reusing the flashing and boots.
Ask each of them the same three questions and the picture clears quickly.
Money questions
- My deductible is 2 percent of what, exactly?
Of the dwelling coverage limit, not of the claim and not of the home’s market value. On a $350,000 dwelling limit, 2 percent is $7,000. It is on the declarations page and it is the single most important number in a hail claim.
- The insurer's estimate is lower than every bid. Now what?
That is common and usually resolvable. Contractors supplement, meaning they document items the adjuster did not scope and ask for them to be added. It is a normal process, it takes time, and a contractor who is good at it is worth having.
- Do I have to spend the insurance money on the roof?
Legally it is your money, subject to any mortgage lender’s requirements, and lenders often require proof of completion. Practically, an unrepaired roof affects your next claim and your next sale.
- Are Class 4 shingles worth the upgrade here?
More so in Colorado than almost anywhere, because insurers frequently discount the premium for them. Get the actual discount figure from your agent before paying for the upgrade, and see the impact resistant page.